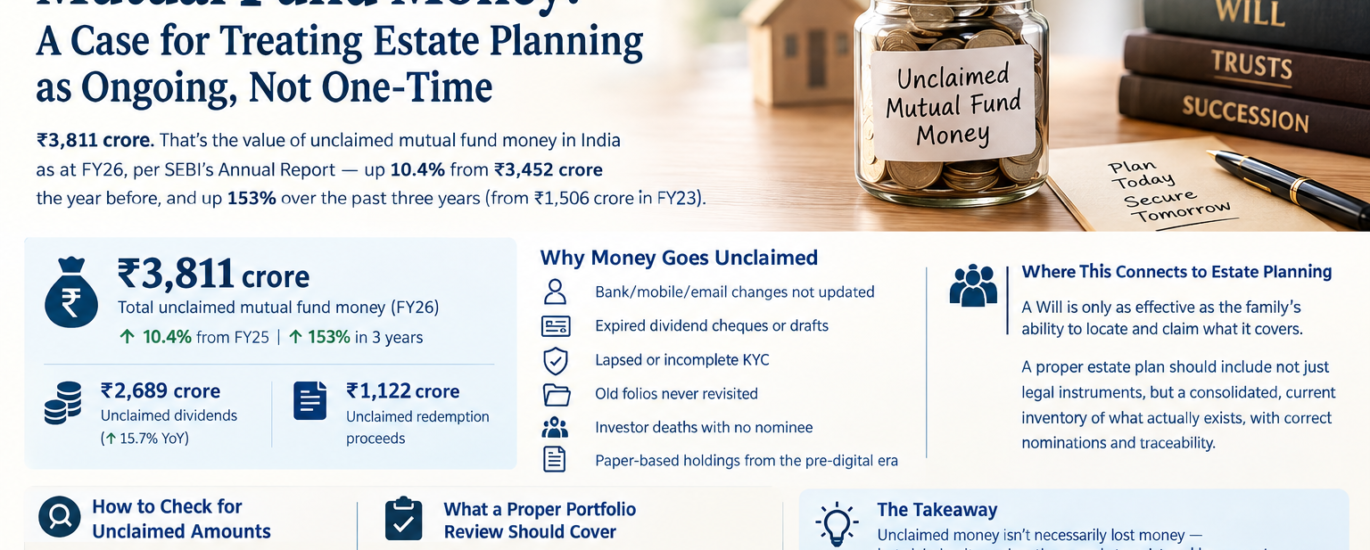
₹3,811 crore. That’s the value of unclaimed mutual fund money in India as at FY26, per SEBI’s Annual
Report — up 10.4% from ₹3,452 crore the year before, and up 153% over the past three years (from
₹1,506 crore in FY23).
Of this, ₹2,689 crore is unclaimed dividends (up 15.7% year-on-year) and ₹1,122 crore is unclaimed
redemption proceeds. The number is large enough to make headlines, but the more useful message
for investors and their families is a quieter one: money can remain invested, or payable, without
anyone actively tracking it.
Why Money Goes Unclaimed
SEBI’s data and industry reporting point to a mix of operational and investor-side causes:
- Bank account, mobile number, or email changes that were never updated with the fund house
or registrar - Physical dividend cheques or demand drafts that expired before being deposited
- KYC details that lapsed or were never completed to current standards
- Folios opened years or decades ago and never revisited
- Investor deaths where no nominee was registered, or where the family was unaware the
investment existed at all - Paper-based holdings from before consolidated, digital record-keeping became standard
Some of these are administrative — a cheque nobody deposited. Others are structural, and this is
where estate planning and portfolio hygiene meet directly: an investment with no registered
nominee, unknown to anyone but the original investor, is functionally unclaimed the moment that
investor is no longer able to manage it themselves.
Where This Connects to Estate Planning
We’re often asked to draft a Will, structure a trust, or plan a cross-border succession — and those
remain the core of the work. But a Will is only as effective as the family’s ability to locate and claim
what it covers. An estate plan that names the right people but doesn’t account for a folio from 2009,
a dividend account with an old address, or a fund house nobody remembers investing with, still
leaves money on the table.
For NRI families in particular, this risk compounds: investments made during an earlier stint in India,
bank accounts tied to addresses that no longer exist, and family members abroad who may not
know what was invested, or where. A proper estate and succession plan should include not just the
legal instruments — Wills, gift deeds, trust structures — but a consolidated, current inventory of
what actually exists, correctly nominated and traceable by the people who’ll eventually need to
claim it.
How to Check for Unclaimed Amounts
For anyone who wants to check now, rather than leave it to their heirs later:
- MITRA on MF Central (mfcentral.com) — SEBI’s tracing tool; enter your PAN, verify by OTP, and
get a consolidated view of inactive folios and unclaimed amounts across fund houses - AMFI’s Investor Corner — search by AMC and PAN or folio number
- CAMS and KFintech — both registrars offer unclaimed-amount lookups and Consolidated
Account Statements - Individual AMC websites, if the fund house is known
For legal heirs claiming on behalf of someone deceased, the process additionally requires a
transmission form and death certificate, with documentation varying depending on whether a
nominee was registered — one more reason nomination, done correctly at the time of investment,
saves considerable difficulty later.
What a Proper Portfolio Review Should Cover
A periodic review should go beyond current holdings and recent performance. It should confirm:
- All investments — including old and inactive folios — are recorded in one consolidated view
- Bank and contact details are current with every fund house and registrar
- KYC is complete and current
- Nomination is registered correctly, and reflects the client’s actual wishes
- No dividends or redemption proceeds are sitting unclaimed
Treated this way, a portfolio review becomes as much a part of financial housekeeping as it is a
performance check.
The Takeaway
Unclaimed money isn’t necessarily lost money — but claiming it requires the records to exist and be
current, which is precisely what a well-maintained estate plan provides. ₹3,811 crore is a useful,
concrete reminder that investing is only half the job. Documenting, consolidating, and keeping that
record current — for yourself and for whoever comes after you — is the other half.
Samir Mahajan is a Chartered Accountant and Partner at Surinder Mahajan & Associates, where he advises NRI
clients on cross-border tax compliance, remittances, and estate and succession planning.